
Review a pivot supplier's financial resilience with identified evidence, qualified interpretation and a clear picture of your program's exposure. Confirm the entity and period behind accounts or credit information, then distinguish historical records, current updates and forward-looking assumptions. A single ratio, missing report or delayed order cannot establish that the supplier will fail. Procurement should separately identify authorised custom work, payment exposure and the dependencies of any fallback route. The purpose is to support a proportionate continuity decision, not publish a solvency verdict. No audited PremFixer financial-report service, company credit rating or guaranteed recovery arrangement is established here; financial and binding legal decisions need qualified advisers.
Hero: concept illustration of example hardware and its application. It is not a factory photograph, tested component or approved production geometry.
Identify whose information the review concerns
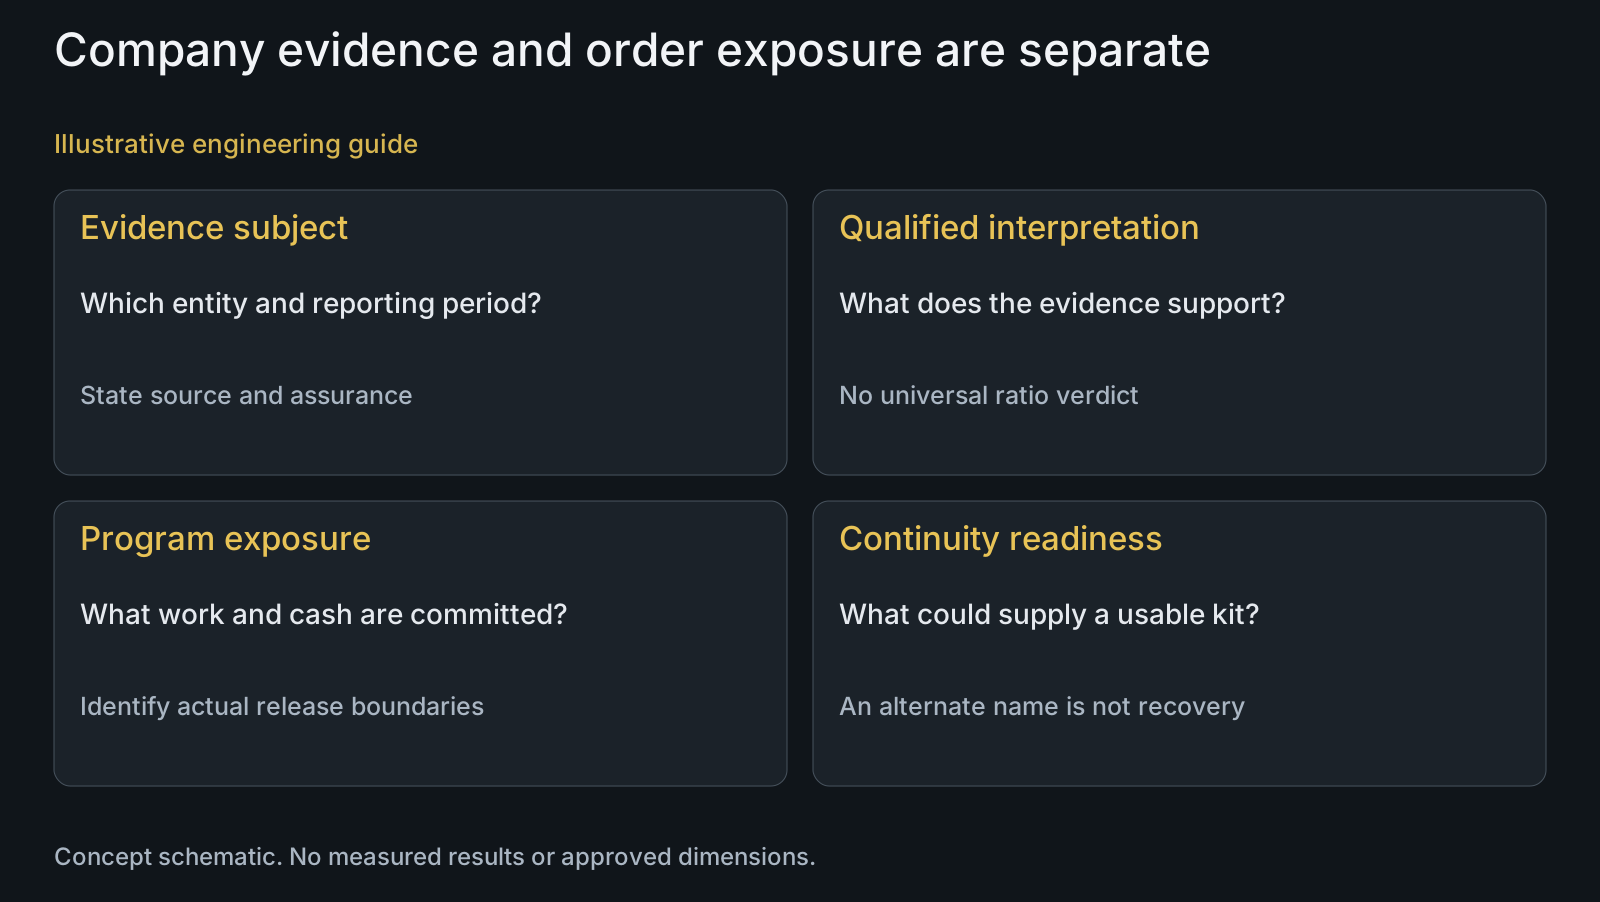
Confirm the proposed contracting entity and producing scope before reviewing financial information. A similarly named company or group report may cover a different subject. Ask the qualified reviewer what the supplied evidence can establish for the entity responsible for your order.
Identify the information's source, period and assurance. Published accounts, management information, a credit-agency view and a supplier explanation are not interchangeable evidence. A report title or bank reference does not independently prove that the current pivot program can be funded through every remaining operation.
The supplier-selection checklist evaluates the proposed manufacturing purchase. Financial resilience adds a different review scope; good technical answers do not substitute for finance expertise, and an attractive financial summary does not establish control of the required bearing interface.
Keep historical evidence and current assumptions distinct
A record can be authentic but describe an earlier condition. Confirm the reporting period and what has changed since then before using it to support a current release decision. A recent download date does not make old financial information current.
The UK Government's supplier financial-standing guidance discusses historical-information limits and qualified, proportionate assessment in its public-procurement context. It is not a mandatory private bicycle-supplier scoring system or a finding about PremFixer.
Where permitted, ask for an explanation of material changes relevant to the order. Distinguish independently supported records from projections and statements that have not been verified. Do not assign an invented probability of failure to fill a missing field or treat a projection as realised cash availability.
| Review subject | What to establish | Unsupported inference to avoid | Next scoped decision |
|---|---|---|---|
| Entity and report scope | Contracting subject, period and assurance | A group or similarly named entity represents this order | Qualified reviewer confirms applicability |
| Historical accounts | Condition represented at that period | Recent retrieval means current financial health | Clarify relevant subsequent changes |
| Projection or management update | Assumptions and available corroboration | Forecast cash treated as realised funds | State the confidence and missing evidence |
| Operational delay | Observed change and actual explanation | One delay proves insolvency or unpaid partners | Investigate the identified route dependency |
| Order exposure | Authorised work, payment events and usable stock | Supplier assessment alone protects the build | Review the next commitment and continuity requirements |
| Fallback proposal | Technical readiness and agreed access boundaries | Alternate name guarantees immediate recovery | Resolve qualified kit output and legal rights separately |
Connect finance questions to a bounded supply concern
Ask which part of the proposed program requires funding before payment: input material, tooling, processing, partner work or finished stock. Finance specialists can assess the evidence relevant to those commitments. Procurement should not prescribe a universal ratio threshold from an unrelated industry.
An operational change can justify a focused question without establishing financial distress. A longer quoted date may reflect the mix, capacity or unresolved requirements. Seek the basis before concluding that it proves unpaid partners or an inability to continue trading.
Use the capacity-assessment guide to separate resource availability from financial interpretation. Likewise, the manufacturing overview identifies in-house and partner scope without asserting actual partner debts or funding arrangements. Keep verified observations and possible explanations separate.
Assess your program's exposure independently
Identify authorised releases, relevant payment milestones and configuration-specific material or work. Then ask how much of the planned build depends on usable stock or future completion. This is a description of the buyer's supply exposure, not a balance-sheet judgement about the supplier.
A fallback must have its own technical readiness. Available drawings, tooling access, approved material and final-condition evidence can affect whether another route could supply the kit. An alternate supplier's existence does not mean the buyer can immediately transfer custom work or take possession of inventory.
The sourcing-resilience guide examines complete-kit output and backup activation. Ownership, access rights and transfer obligations need their own agreement and qualified legal review. Do not infer enforceable recovery rights from a stock label or a general supply-chain plan.
Review old accounts alongside an unqualified fallback
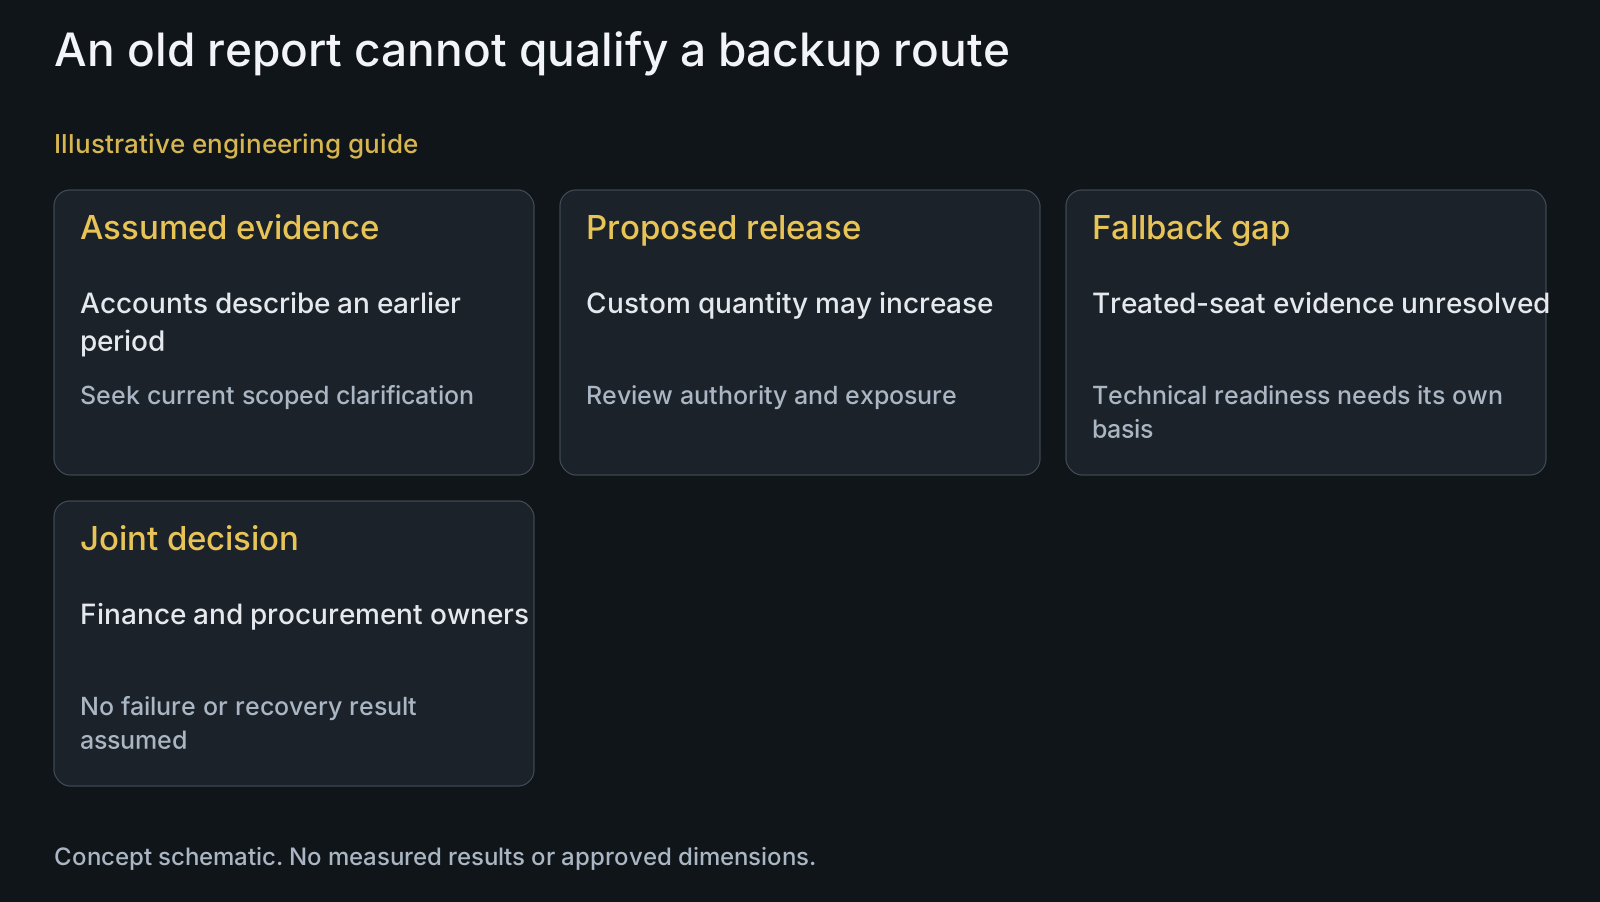
Illustrative engineering example: assume the buyer has financial information for an earlier period and is considering a larger custom pivot release. A potential alternate supplier has not established the required treated-seat evidence. No actual company, account balance, adverse financial event or failed delivery is assumed.
The finance reviewer identifies what the earlier evidence can support and what current clarification is needed. Procurement separately checks the proposed release exposure and the missing qualification basis at the fallback. Neither a reassuring old report nor an extra supplier name closes both decisions.
The team can discuss a narrower authorised release, additional evidence or a bounded fallback assessment with the appropriate owners. The example chooses no financing strategy and predicts no failure. It shows how to keep financial uncertainty and practical recovery readiness visible without inventing a solvency conclusion.
Agree confidential follow-up and proportionate actions
Request only the information appropriate to the decision and agree confidentiality, access and use. Restricted disclosure can reflect legitimate commercial sensitivity; it should not automatically become an accusation. Equally, record what cannot be verified instead of treating a polished presentation as proof.
Connect a concern to a proposed action and its owner: clarification, reassessment of an uncommitted release, a delivery-scope discussion or a fallback-readiness review. Each changes different exposure and may need agreement. Do not promise that split shipments, deposits or buyer-owned material always eliminate continuity risk.
The payment-milestone guide, materials overview and knowledge center support adjacent purchase definitions. Ask PremFixer about available, permitted evidence for the actual relationship. This article does not offer investment advice, financial guarantees, public credit scoring or an unverified audited-report service.
Questions buyers need to confirm
Can one ratio predict whether a pivot supplier will fail?
No single ratio should be treated as a reliable verdict. Use qualified interpretation of identified evidence, time periods and context. Do not invent a failure probability or apply an unrelated sector threshold to fill missing information.
Does a recent download make financial accounts current?
No. Check the period the record represents and relevant subsequent changes. Retrieval time and financial reporting time are different. State whether later information is independently supported or only a projection or explanation.
Does a delayed order prove financial distress?
No. It is an observation requiring its actual cause to be examined. Capacity, route changes and unresolved requirements can affect timing. Seek the relevant evidence instead of asserting insolvency or unpaid partners without support.
Should a supplier be rejected for withholding private information?
Not automatically. Agree a proportionate evidence scope and confidential review, then record the remaining limitation. Legitimate sensitivity and unanswered risk are different subjects; neither a refusal nor an attractive presentation establishes a solvency conclusion.
Does having a backup supplier remove our financial supply risk?
No. Check its qualified output, required inputs and agreed access or transfer rights. A name alone does not make an acceptable pivot kit available. Finance, engineering and legal questions need their respective decision owners.
Can buyers request an audited PremFixer financial report?
Discuss what relevant evidence is available and permitted for the specific relationship. No public audited-report service is established here. Use an agreed confidential commercial channel and qualified advisers rather than assuming that website manufacturing content supplies financial assurance.
Technical references and scope
UK Government supplier economic and financial standing guidance. Public-procurement context, qualified/proportionate assessment, historical-information limitations and confidential evidence. Relevant sections read; not private-OEM legal requirements, adopted ratio thresholds or a judgement on PremFixer.
Explore related component, material and sourcing decisions in the customer decision knowledge center. For a drawing review, use the Drawing/BOM RFQ path.
Define the evidence and exposure for a supplier-continuity review
Send the drawing, STEP file or sample, BOM, planned release quantities, delivery milestones and continuity concern through the Drawing/BOM RFQ path. Identify authorised work and the evidence scope your qualified reviewers need. Agree a confidential channel for sensitive financial material; PremFixer can discuss available project information without promising a credit verdict or recovery guarantee.
Discuss the drawing and BOM